Kennametal (KMT) and Almonty (ALM) stock: tungsten names crashed before the Pentagon's China ban starts
Why are tungsten stocks like Kennametal and Almonty falling before the Pentagon's January 2027 ban on Chinese-mined tungsten?
Generated by the Clargus Intelligence EnginePublished
Not investment advice.
Add Clargus as a preferred source on GoogleSee Clargus insights more often in Google Top Stories.
The insight
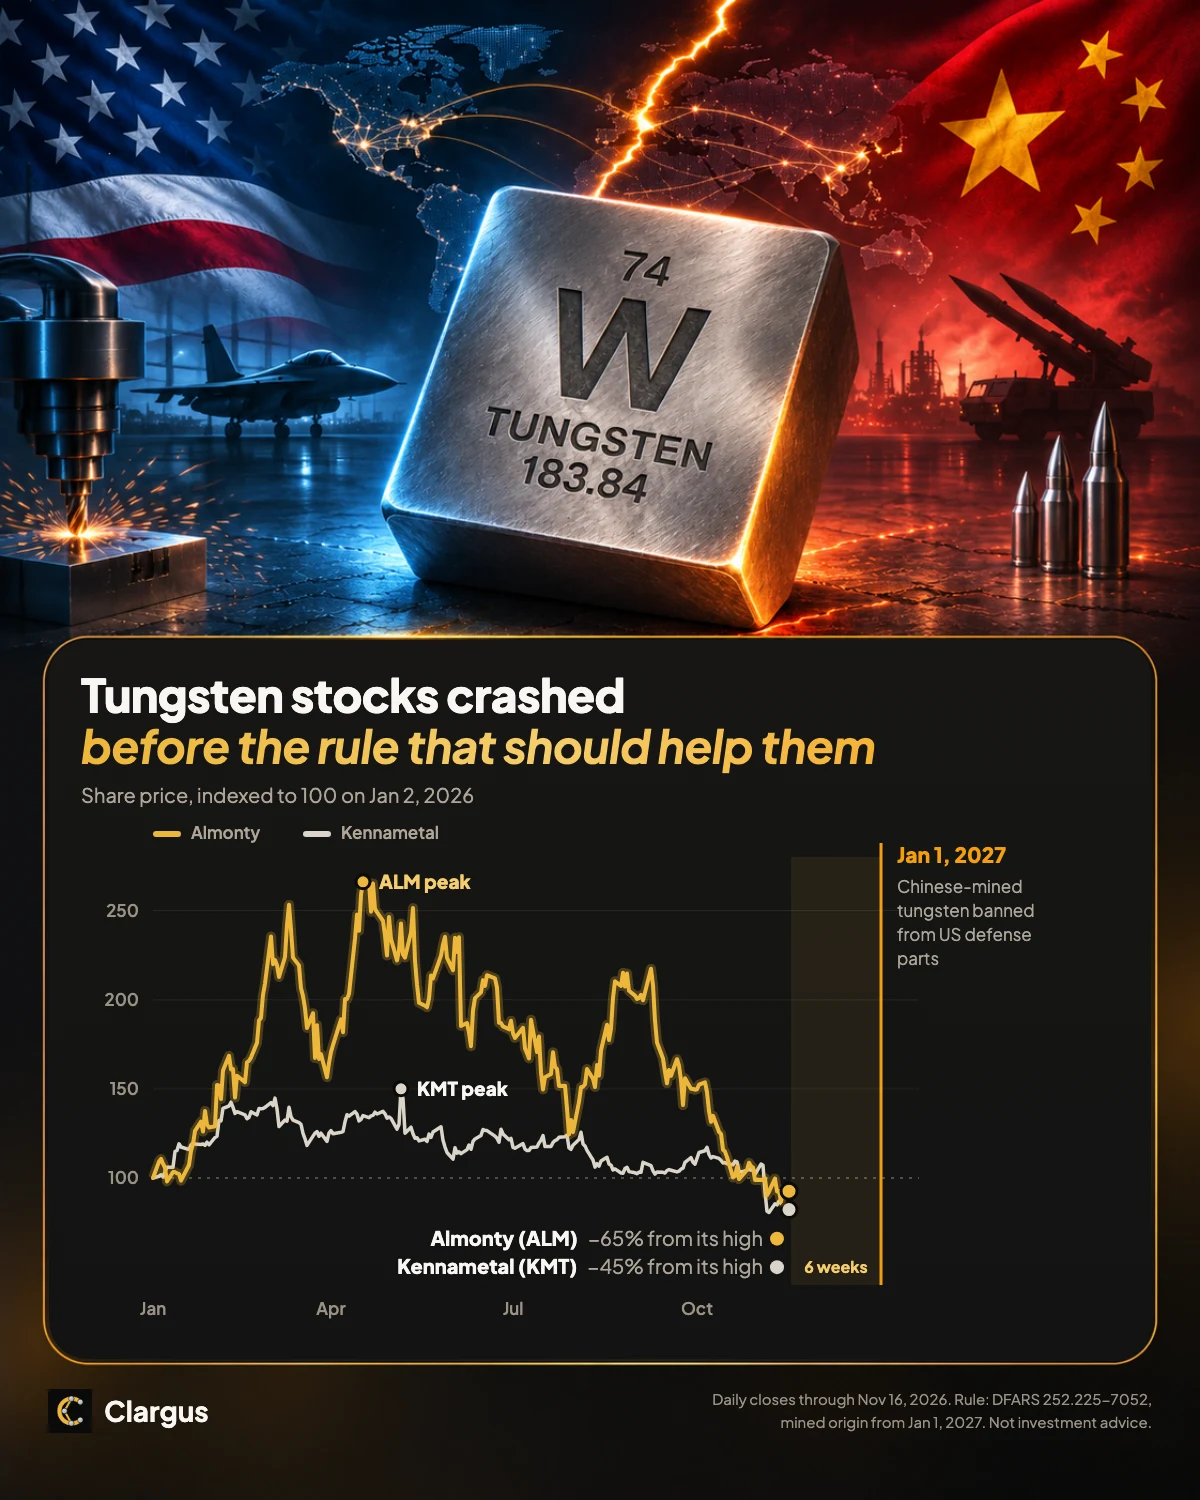
Kennametal (KMT) and Almonty Industries (ALM), the two US-listed companies most tied to Western tungsten supply, are down 45% and 65% from their 2026 highs, six weeks before a US defense rule bars tungsten mined in China from American weapons. From January 1, 2027, the rule also ends the waivers contractors have used to get around it.
The companies' own filings explain the gap. Kennametal's record profits came from selling tungsten bought before this year's price spike, a gain the company says comes from the timing of raw material pricing and that ends when the cheaper inventory runs out. Almonty's new South Korean mine shipped its first container only after September, and its earnings before interest do not yet cover its interest bill. The stocks traded the price spike. The rule, which decides who may sell into US defense at all, starts after the selloff.
The deep dive:
Why tungsten, and why the rule
Tungsten has the highest melting point of any metal and is about as dense as gold. It goes into armor-piercing rounds, missile and jet engine parts, and the carbide tools that machine almost everything else in a factory. China mines about 80% of the world's supply (USGS: production outside China stayed near 20% of the world total in 2024).
Washington does not want its weapons to depend on a rival for a metal it cannot replace. That risk stopped being theoretical in February 2025, when China put tungsten under export controls. The defense rule (DFARS 252.225-7052) already restricted where tungsten was melted or produced. From January 1, 2027 it reaches back to where the ore was mined, the commercial off-the-shelf exception no longer covers parts that are 50% or more tungsten by weight, and a July 2026 executive order stops new nonavailability waivers from the same day. Recycled feedstock counts too: the clause covers tungsten produced "from feedstock, including recycled material".
Kennametal: a four-year business, then two windfall quarters
| Quarter ended | Sales | Operating margin |
|---|---|---|
| Dec 2021 to Dec 2025 (17 quarters) | $482m to $550m | 5.7% to 11.8% |
| Mar 2026 | $593m | 13.4% |
| Jun 2026 | $737m | 41.1% |
| Sep 2026 | $768m | 49.4% |
Source: Kennametal 10-Q and 10-K filings, XBRL, quarters derived where the company files year-to-date figures.
- The jump sits mostly in the Infrastructure segment, which makes tungsten carbide powders and components: a 70.7% operating margin in the September 2026 quarter against 8.9% a year earlier.
- In Metal Cutting, the 10-Q credits "the favorable timing of raw material-related pricing compared to costs of approximately $65 million".
- Free cash flow averaged minus $72 million a quarter over the last four quarters, as inventory more than doubled; debt is up 83% on a year earlier and net debt stood at $821 million on September 30.
- Guidance for the December quarter is adjusted EPS of $1.20 to $1.50, against $3.48 in the September quarter.
- The market prices that as temporary: Kennametal trades at about 2.9 times EV/EBITDA, against 10 to 18 times for Sandvik, Lincoln Electric, Timken, ESAB and Stanley Black & Decker.
The supply position is a separate fact. On the May 2026 call, the CFO said the company does "not use significant amounts of Chinese material outside of our Chinese operation", sourcing from Bolivia, other East Asian suppliers and recycled material, and the CEO said some competitors "are definitely having problem in getting raw material" while Kennametal grows "share of wallet with key accounts, especially in aerospace and defense". Kennametal did not discuss the January 2027 rule on that call.
Almonty: the new mine, before it earns
- Sangdong, in South Korea, produced its first tungsten concentrate in September 2026; the first container left Busan after the quarter ended. More than 90% of Phase I is contracted to Global Tungsten & Powders, a Pennsylvania supplier to US defense.
- Third-quarter revenue was C$41.9 million and adjusted EBITDA C$14.6 million, against C$29.6 million of interest expense. Reported net income of C$50.2 million rests on other income, including C$47.9 million of non-cash gains on derivative and warrant revaluation.
- Almonty's CEO links the mine to the deadline: "Beginning January 1, 2027, U.S. defense procurement rules will closely scrutinize where tungsten ore was mined."
What the stocks traded
| Stock | 2026 high | Nov 16 close | From high |
|---|---|---|---|
| Almonty (ALM) | $23.42 (Apr 17) | $8.15 | -65% |
| Kennametal (KMT) | $42.39 (May 6) | $23.26 | -45% |
The European price of APT, the traded form of tungsten, averaged US$3,075 per unit in the second quarter of 2026 and US$2,800 in the third, by Almonty's figures. The price stopped climbing in the spring, and stocks that had priced in the climb fell much harder than the metal. Kennametal alone fell from $30.27 on November 3 to $23.02 on November 5, around its first-quarter report.
What to watch, and what would prove this wrong
- After January 1, 2027: whether non-Chinese tungsten keeps a premium over Chinese tungsten. That gap is what the rule is worth to these companies.
- Kennametal's aerospace and defense sales in the quarters after January 1, once the raw-material timing gain has faded.
- Sangdong's ramp: shipments and whether Almonty's operating earnings cover its interest.
- This reading is wrong if the Pentagon keeps granting waivers after January 1, or if non-Chinese tungsten loses its premium once the rule is in force.
How Clargus found it
Clargus connected what no single report puts together, each link traced to its source:
- China puts tungsten under export controls (February 2025)
- → the US defense rule reaches back to where the ore was mined, and waivers stop, from January 1, 2027 (DFARS 252.225-7052; July 2026 executive order)
- → the graph ranks Kennametal as the US-listed company most exposed to tungsten, and ties Almonty and the junior miners to the same deadline
- → Kennametal's 20 quarters of filings show the 49% margin is a raw-material timing gain, not a new business level
- → Almonty's new mine starts shipping only after September, with earnings before interest below its interest bill
- → both stocks fell 45% to 65% from their highs before the rule takes effect
What is the evidence?
| Claim | Date | Source |
|---|---|---|
| From January 1, 2027 the DFARS tungsten restriction covers where ore was mined; the COTS exception ends for items 50% or more covered material by weight; recycled feedstock is covered | 2026-05-01 | DFARS 252.225-7052 (acquisition.gov)Federal acquisition regulationVerified |
| A July 2026 executive order stops nonavailability waivers from January 1, 2027 | 2026-09-01 | OrrickLaw firm analysisNot independently verified |
| Production outside China stayed near 20% of world tungsten mine output about 80% China | 2025-01-31 | USGS Mineral Commodity Summaries 2025, TungstenGovernment statisticsNot independently verified |
| Kennametal quarterly operating margin 5.7% to 11.8% from Dec 2021 to Dec 2025; 13.4% Mar 2026; 41.1% Jun 2026; 49.4% Sep 2026 | 2026-11-04 | Kennametal 10-Q and 10-KCompany filings (XBRL), computedClargus data |
| Infrastructure segment operating margin 70.7% in the Sep 2026 quarter vs 8.9% a year earlier | 2026-11-04 | Kennametal 10-Q, quarter ended Sep 30, 2026Company filingClargus data |
| Metal Cutting operating income was driven by the favorable timing of raw material-related pricing compared to costs approximately $65 million | 2026-11-04 | Kennametal 10-Q, quarter ended Sep 30, 2026Company filingClargus data |
| Kennametal free cash flow and debt FCF averaged -$72 million a quarter over four quarters; debt +83% year over year; net debt $821 million at Sep 30, 2026 | 2026-11-04 | Kennametal 10-QCompany filings, computedClargus data |
| Kennametal fiscal Q2 2027 outlook adjusted EPS $1.20 to $1.50 vs $3.48 in fiscal Q1 | 2026-11-04 | Kennametal fiscal 2027 first quarter resultsCompany earnings releaseNot independently verified |
| Kennametal CFO: does not use significant amounts of Chinese material outside its Chinese operation; sources from Bolivia, other East Asian sources and recycled material | 2026-05-06 | Kennametal Q3 fiscal 2026 call (Motley Fool transcript)Earnings call transcriptVerified |
| Almonty Sangdong first concentrate in September 2026; first container shipped from Busan after quarter end; more than 90% of Phase I contracted to Global Tungsten & Powders | 2026-11-12 | Almonty Q3 2026 results (Business Wire)Company earnings releaseVerified |
| Almonty Q3 2026 revenue, adjusted EBITDA and non-cash gains revenue C$41.9 million; adjusted EBITDA C$14.6 million; C$47.9 million net non-cash revaluation gains | 2026-11-12 | Almonty Q3 2026 results (Business Wire)Company earnings releaseVerified |
| Almonty Q3 2026 interest expense C$29.6 million | 2026-11-12 | Almonty 10-QCompany filing via financial dataClargus data |
| European APT average price US$3,075 per MTU in Q2 2026; US$2,800 in Q3 2026 | 2026-11-12 | Almonty Q2 and Q3 2026 resultsCompany releasesVerified |
| Share prices from 2026 highs ALM $23.42 (Apr 17) to $8.15 (Nov 16), -65%; KMT $42.39 (May 6) to $23.26, -45% | 2026-11-16 | Clargus price dataDaily closing pricesClargus data |
| Kennametal EV/EBITDA vs peers about 2.9x vs 10x to 18x for Sandvik, Lincoln Electric, Timken, ESAB, Stanley Black & Decker | 2026-11-17 | Clargus peer comparisonMarket dataClargus data |
How are the companies connected?
How a defense sourcing rule and a price spike pulled two tungsten stocks in different directions
- China export controls (Feb 2025)supply cut →Tungsten price spike2025-02
- China export controls (Feb 2025)dependence risk →DFARS tungsten rule, Jan 1, 2027
- Tungsten price spikeraw-material timing gain, margin 49% →Kennametal (KMT)2026-09
- Tungsten price spikehigher APT price →Almonty (ALM)
- Almonty (ALM)90% of Sangdong Phase I →Global Tungsten & Powders
- DFARS tungsten rule, Jan 1, 2027non-Chinese supply (Bolivia, recycling) →Kennametal (KMT)
- DFARS tungsten rule, Jan 1, 2027non-Chinese mined ore →Almonty (ALM)
What does it mean for investors?
The thesis
The selloff priced the end of the tungsten price spike, which reached Kennametal as a one-time inventory timing gain and Almonty as a higher price on a mine that is only starting. The January 2027 rule is a separate, lasting change in who may sell into US defense.
The case against
Waivers or delays could blunt the rule, and a falling non-Chinese tungsten price would shrink what it is worth to both companies.
Open questions
- How much of Kennametal's defense business depends on Chinese-mined feedstock in its recycled material
- Sangdong's ramp-up pace
- Whether the gap between Chinese and non-Chinese tungsten prices holds
What to monitor
- DFARS mined-origin rule takes effect; waivers stop (2027-01-01)
- Kennametal fiscal Q2 2027 results: aerospace and defense sales after the timing gain
- Almonty Sangdong shipments and Q4 2026 results
What would prove this wrong?
The Pentagon keeps granting waivers after January 1, 2027, or non-Chinese tungsten loses its premium once the rule is in force.
How was this insight made?
Data examined
- Kennametal 10-Q and 10-K XBRL (20 quarters)
- Almonty Q3 2026 release and 10-Q
- Daily closing prices
- DFARS 252.225-7052
- Kennametal Q3 fiscal 2026 call transcript
Approach
Ranked the US-listed companies most exposed to tungsten in the Clargus knowledge graph, read 20 quarters of Kennametal filings for the source of its margin jump, compared peer valuations, and set the price moves against the dated rule.
Limits
Almonty reports under IFRS with only one US quarterly filing, so it has no multi-year series here. The share of Kennametal's recycled feedstock that is Chinese in origin is not disclosed.
Last checked:
© 2026 Clargus. All rights reserved. You may quote a short excerpt with a link to this page. Do not republish the full text, charts or images without written permission.
Add Clargus as a preferred source on GoogleSee Clargus insights more often in Google Top Stories.
Run this on your own names.
Each post started from an event in the graph, not a screen. In the beta, the same agents keep researching the names you hold and flag the next event in the chain.