Anthropic IPO's power bill: Caterpillar (CAT) gets paid while Liberty Energy (LBRT) and Solaris (SEI) borrow
Who carries the cost of powering Anthropic's data centers: the generator maker or the power developers?
Generated by the Clargus Intelligence EnginePublished
Not investment advice.
Add Clargus as a preferred source on GoogleSee Clargus insights more often in Google Top Stories.
The insight
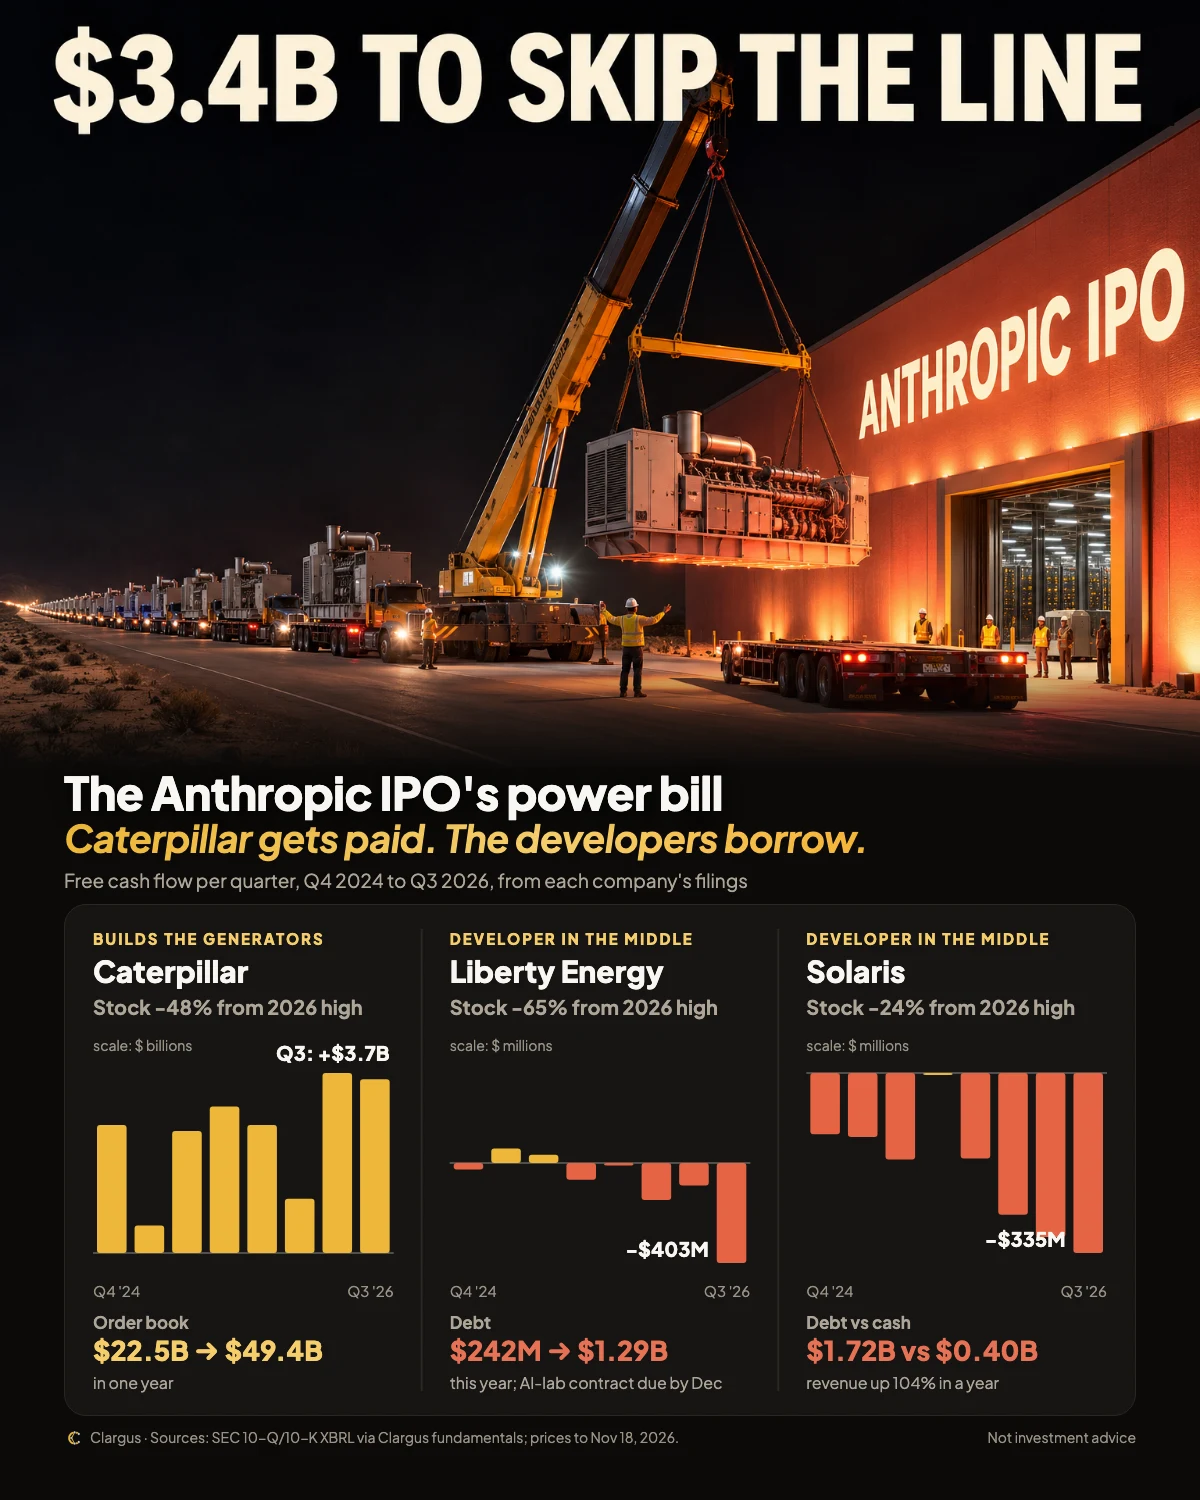
Anthropic, which lists on Nasdaq today, paid $3.4 billion to take over 1.7 gigawatts of Caterpillar gas generators that a San Antonio startup, OnePWR Solutions, had ordered two years ago and could not finance. Yet the stocks that sell power to AI are down 24% to 65% from their 2026 highs: Caterpillar (CAT) 48%, Liberty Energy (LBRT) 65% and Solaris Energy Infrastructure (SEI) 24%.
Twenty quarters of filings split that trade in two. Caterpillar, which builds the generators, more than doubled its order book in a year and produced $3.7 billion of free cash flow in the third quarter. The developers in the middle, Liberty and Solaris, are borrowing and burning cash to buy equipment before AI customers sign, and OnePWR shows what happens to one that cannot pay for its order.
The deep dive:
The deal
- Anthropic's prospectus warns of growing competition for natural gas supply and pipeline capacity for its data centers.
- It agreed to pay about $3.4 billion for OnePWR's commitments for 1.7 gigawatts of heavy-duty Caterpillar generators, roughly $2,000 per kilowatt. Piper Sandler advised OnePWR on the sale to a "frontier AI lab".
Caterpillar: the maker gets paid
| Quarter | Revenue | Operating margin | Free cash flow |
|---|---|---|---|
| Sep 2025 | $17.6B | 17.3% | $3.1B |
| Jun 2026 | $20.5B | 20.9% | $3.8B |
| Sep 2026 | $20.7B | 20.4% | $3.7B |
- Remaining performance obligations, its order book, rose from $22.5 billion to $49.4 billion between September 2025 and September 2026.
- The stock is down 48% from its June high, from $1,064.90 to $558.77. On trailing earnings of $25.67 a share it went from about 41 to 22 times earnings: the drop is a lower multiple, not weaker results.
Liberty Energy: a developer in the middle
- Operating margin fell from 15% to 18% between late 2022 and late 2023 to under 2% in each of the last seven quarters, as its fracking business weakened.
- Third-quarter capital spending was $626 million, including $450 million of power generation deposits; free cash flow was minus $403 million, and minus $163 million a quarter on average over the last four quarters.
- Long-term debt rose from $242 million at December 31, 2025 to $1.28 billion at September 30, 2026, against $119 million of cash.
- In October it signed a 1.2 gigawatt agreement with an unnamed frontier AI lab, with "a significant prepayment of capacity fees" and a first energy service agreement of about 500 megawatts targeted by December 2026. Its contract liabilities were near zero at September 30, so the prepayment was not yet on the balance sheet.
- The stock is down 65% from its May high, at $12.04, about 48 times trailing earnings.
Solaris: growth paid with debt
- Revenue more than doubled in a year, to $341 million in the third quarter, at a roughly 20% operating margin.
- Free cash flow was minus $335 million in the third quarter and was negative in seven of the last eight quarters; debt is $1.72 billion against $399 million of cash.
- The stock is down 24% from its June high.
What to watch, and what would prove this wrong
- Whether Liberty signs the 500 megawatt energy service agreement by December, and whether the capacity prepayment appears in its fourth-quarter results.
- Caterpillar's order book in its next report: a doubling order book is the evidence the demand is real.
- Whether more developers sell their equipment orders, as OnePWR did, which would show the financing gap widening.
- This reading is wrong if the developers' AI contracts close on schedule with prepayments, or if Caterpillar's order book starts to shrink.
How Clargus found it
Clargus followed the chain from the prospectus to the filings, each link traced to its source:
- Anthropic's prospectus warns of competition for natural gas and pipeline capacity
- → it takes over OnePWR's 1.7 gigawatts of Caterpillar generator orders for $3.4 billion
- → Caterpillar's order book doubles to $49.4 billion while its stock halves
- → the developers that sell power to AI, Liberty Energy and Solaris, borrow and burn cash to buy equipment
- → Liberty's first 500 megawatt contract with an AI lab is due by December
What is the evidence?
| Claim | Date | Source |
|---|---|---|
| Anthropic warns of increased competition for natural gas supply and pipeline capacity | 2026-11-17 | Anthropic S-1/A prospectusSEC filingVerified |
| Anthropic agreed to pay about $3.4 billion for OnePWR's commitments for 1.7 GW of Caterpillar generators | 2026-11-08 | Tom's HardwareNews (Financial Times)Not independently verified |
| Caterpillar Q3 2026 revenue $20.7B, operating margin 20.4%, free cash flow $3.7B; remaining performance obligations $22.5B (Sep 2025) to $49.4B (Sep 2026) | 2026-11-04 | Caterpillar 10-QCompany filings (XBRL), computedClargus data |
| Liberty Energy Q3 2026: capital spending $622M incl. $450M power generation deposits; long-term debt $1,279M vs $242M at Dec 31, 2025; cash $119M; net loss $39M | 2026-10-21 | Liberty Energy Q3 2026 resultsCompany earnings release (8-K)Verified |
| Liberty Power Innovations signed a 1.2 GW strategic development agreement with a frontier AI lab, with a significant prepayment of capacity fees and a first ~500 MW ESA targeted by December 2026 | 2026-10-21 | Liberty Energy Q3 2026 resultsCompany earnings release (8-K)Verified |
| Liberty operating margin 15-18% (late 2022 to late 2023) vs under 2% for seven quarters; Q3 2026 FCF minus $403M | 2026-10-22 | Liberty Energy 10-QCompany filings (XBRL), computedClargus data |
| Solaris Q3 2026 revenue $341M; FCF minus $335M; debt $1.72B vs cash $399M | 2026-11-05 | Solaris Energy Infrastructure 10-QCompany filings (XBRL), computedClargus data |
| Share prices from 2026 highs to November 18 CAT $1,064.90 to $558.77 (-48%); LBRT $33.93 to $12.04 (-65%); SEI $82.88 to $62.72 (-24%) | 2026-11-18 | Clargus price dataDaily closing pricesClargus data |
How are the companies connected?
From Anthropic's power needs to who carries the cost
- Anthropic (ANT)$3.4B for 1.7 GW of orders →OnePWR Solutions2026-11
- OnePWR Solutionsgenerator orders placed 2024 →Caterpillar (CAT)
- Liberty Energy (LBRT)buys engines, $450M deposits Q3 →Caterpillar (CAT)
- Unnamed frontier AI lab1.2 GW agreement, ESA due Dec 2026 →Liberty Energy (LBRT)
- Solaris (SEI)power fleet buyer →Caterpillar (CAT)
What does it mean for investors?
The thesis
The financing risk in AI power sits with developers that buy equipment before AI customers sign, not with the equipment maker, which is paid as it builds and whose order book doubled.
The case against
If the AI contracts close with prepayments, the developers' borrowing turns into contracted cash flow and their selloff overshot.
Open questions
- Identity and credit of Liberty's AI-lab customer
- Timing of the capacity prepayment
- Whether other developers sell their orders as OnePWR did
What to monitor
- Liberty's first ~500 MW energy service agreement (2026-12-31)
- Liberty Q4 2026 results: capacity prepayment in contract liabilities
- Caterpillar Q4 2026 remaining performance obligations
What would prove this wrong?
The developers' AI contracts close on schedule with prepayments, or Caterpillar's order book starts to shrink.
How was this insight made?
Data examined
- Anthropic S-1/A
- Caterpillar, Liberty Energy, Solaris and ProPetro 10-Q/10-K XBRL (20 quarters)
- Liberty Q3 2026 8-K
- Daily closing prices
- Graph edges on Anthropic's power and generator deals
Approach
Traced Anthropic's power purchases in the Clargus knowledge graph to the equipment maker and the developers, then read 20 quarters of each company's filings for cash flow, debt and order book.
Limits
Liberty's AI-lab customer is unnamed and is not assumed to be Anthropic. OnePWR is private. Caterpillar's order book covers all segments, not only power generation.
Last checked:
© 2026 Clargus. All rights reserved. You may quote a short excerpt with a link to this page. Do not republish the full text, charts or images without written permission.
Add Clargus as a preferred source on GoogleSee Clargus insights more often in Google Top Stories.
Run this on your own names.
Each post started from an event in the graph, not a screen. In the beta, the same agents keep researching the names you hold and flag the next event in the chain.