Vicor gets the power into AI chips. Now it is defending that at the ITC.
Not investment advice.
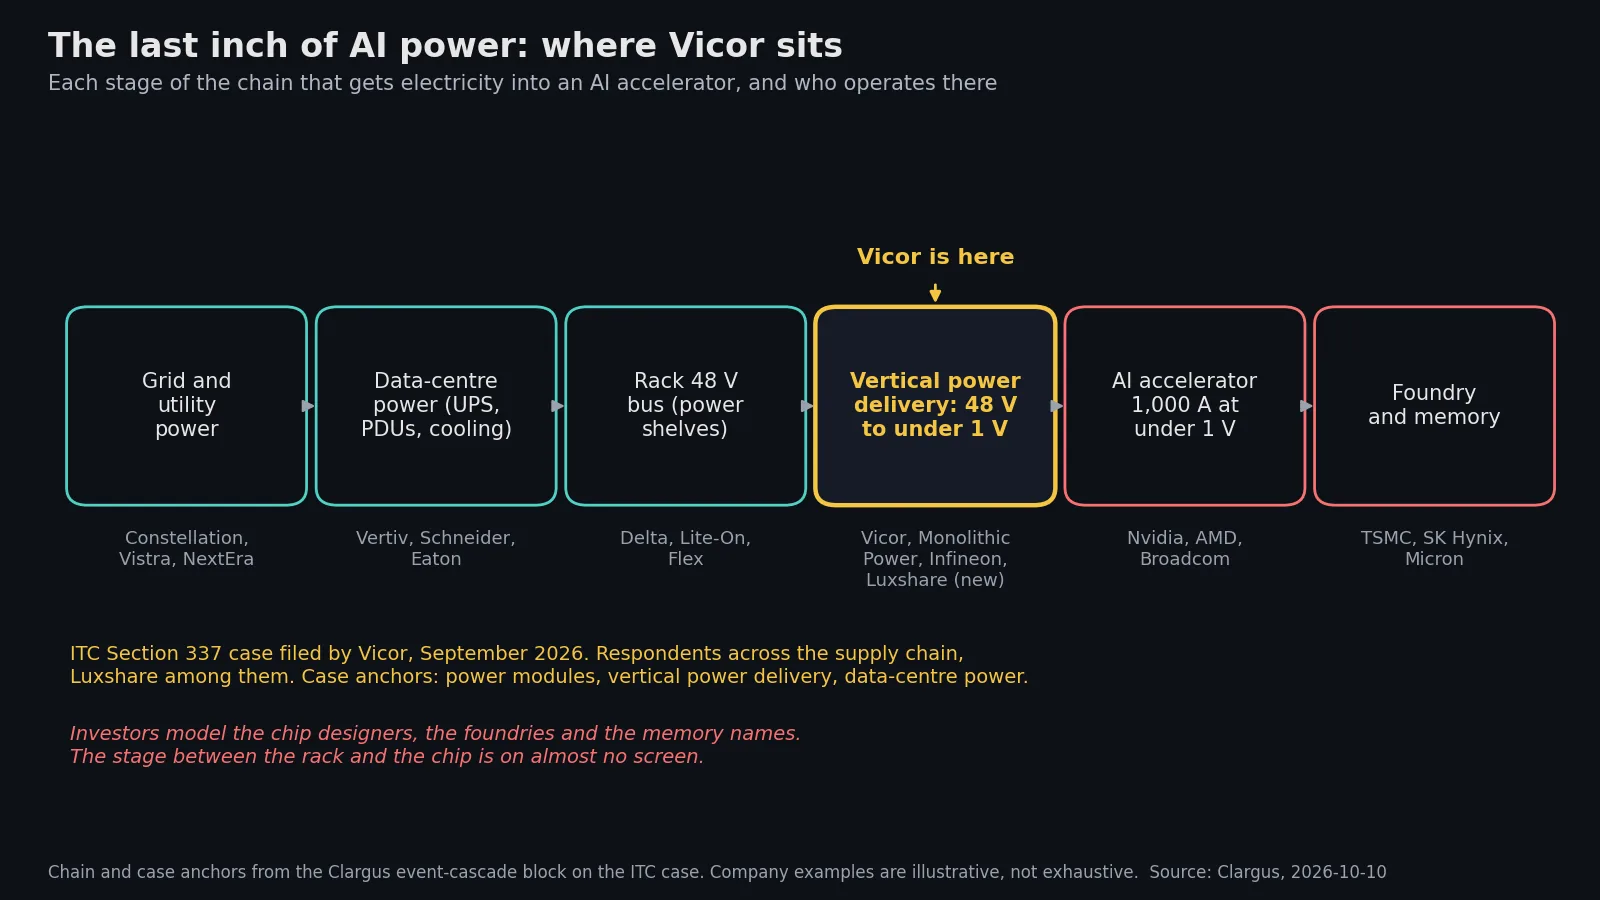
Everyone is watching who makes the next AI chip.
Far fewer are asking who gets the electricity into it.
A modern accelerator wants roughly a thousand amps at under a volt. Moving that across a board without losing it as heat is a hard engineering problem, and the industry is converging on 48-volt vertical power delivery: converters sitting directly under the chip.
Vicor builds those. Revenue grew 49% last quarter, net income was $50M, and there is no debt on the balance sheet.
It has also opened an ITC patent case against a list of respondents across the electronics and computing supply chain, Luxshare among them. Clargus flagged the case because its anchors were not consumer electronics: power modules, vertical power delivery, data-centre power. An AI infrastructure fight filed as a patent dispute.
What the case proves is limited. Enforcement shows Vicor believes the IP matters. It does not show the part is irreplaceable, and a design-around narrows the moat.
The stock is 30% off its high after a 143% year. It is filed under "electronic components" and covered by analysts who think in connectors, while its demand driver is the hyperscaler capex that earns 40x one layer up.
The chip designers, the foundries and the memory names are on every screen. The stage between the rack and the chip is on almost none. That gap is the opportunity. The case is the reason to look now.
Run this on your own names.
Each post started from an event in the graph, not a screen. In the beta, the same agents keep researching the names you hold and flag the next event in the chain.